Why Manufacturing HBM Cannibalizes Global Silicon Wafer Capacity
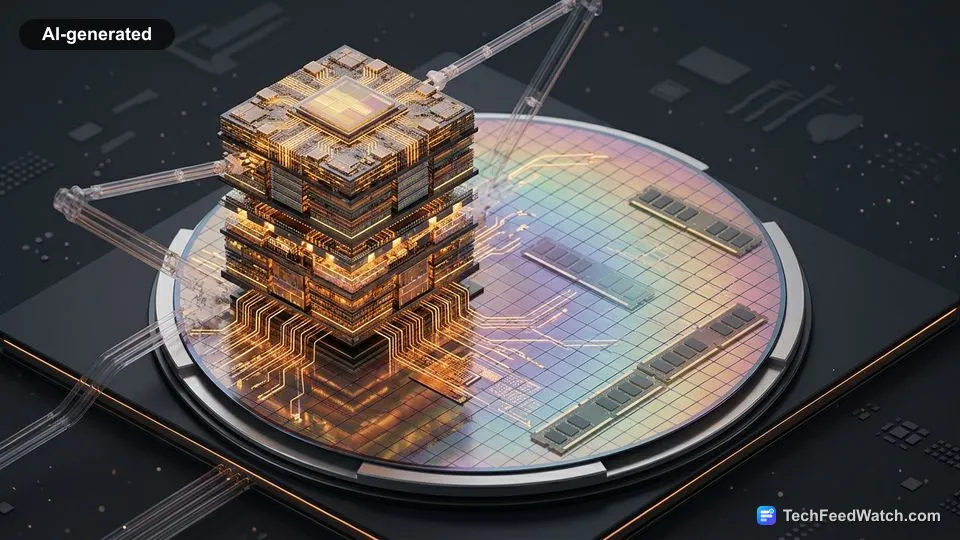
The memory industry operates under strict physical manufacturing limitations. Building memory chips requires high-purity silicon wafers processed through photolithography tools inside specialized semiconductor fabrication plants.
When demand for high-end AI components accelerates, manufacturers cannot instantaneously summon new fabrication plants. Instead, they repartition existing wafer production lines.
HBM designs consume disproportionate amounts of physical wafer area compared to standard DRAM modules. According to Micron Technology HBM Design Architecture Fellow Raghu Sreeramaneni at the Hot Chips 2026 conference on August 23, 2026, HBM3E requires roughly three times the silicon wafer area of conventional DDR5 for the same bit capacity due to massive interface parallelism and through-silicon via (TSV) architecture.
Every single wafer turned into stacked AI memory directly reduces the raw output of mainstream memory modules.
According to TrendForce, Samsung Electronics Executive Vice President Kim Taewoo stated in September 2026 that HBM is projected to consume nearly 30 percent of the memory industry’s total DRAM wafer capacity in 2027, up from roughly 20 percent in 2026. The shift exposes the fundamental physical reason NVIDIA AI Chips: Why Memory Technology Is Their Secret Weapon remains a central industry narrative.
The direct operational trade-offs required by HBM manufacturing include:
- Silicon Area Loss: The sheer physical footprint of vertical interconnects reduces total functional bit yields per silicon wafer.
- Cleanroom Packaging Bottlenecks: Advanced packaging and micro-bump bonding require extra fabrication steps, pulling machinery away from conventional assembly lines.
- Yield Falloff: Stacking multiple dies means that a single flawed layer can ruin an entire multi-die package, increasing silicon waste.
Surging Server and Consumer RAM Prices from Fab Reallocation
The strategic pivot toward HBM creates an acute supply shock for standard DRAM across enterprise and consumer sectors. The DRAM manufacturing sector is concentrated among a few dominant firms.
According to the Center for Strategic and International Studies (CSIS), market research firm TrendForce estimated that Samsung, SK Hynix, and Micron accounted for 90.5 percent of global DRAM sales in the fourth quarter of 2025. Because these three conglomerates command the vast majority of output, their allocation strategies dictate global component availability.
When these major suppliers reprioritize production lines toward high-margin AI packages, baseline supply drops sharply. According to TrendForce, global DRAM contract prices jumped by 93 percent to 98 percent quarter-over-quarter in the first quarter of 2026 as manufacturers prioritized high-margin HBM and server memory.
Buyers purchasing conventional memory for server upgrades or personal devices suddenly face pricing spikes across distribution channels.
The escalation hits standard server infrastructure especially hard. According to Counterpoint Research tracking data, the market price for 64GB DDR5 server memory modules climbed 3.5 times between the third quarter of 2025 and the first quarter of 2026. Data centers expanding basic cloud storage, enterprise databases, or standard web operations must pay massive premiums simply to procure ordinary system memory.
Uneven Shortages and Market Factors Softening the Memory Squeeze
The memory shortage does not impact all product segments identically. Legacy computing hardware that runs on mature DDR4 or DDR3 designs operates on older, fully amortized manufacturing lines that cannot convert to cutting-edge HBM production. Consequently, consumer routers, industrial controllers, and budget motherboards using older DRAM standards face less severe price spikes.
Countervailing dynamics also prevent an absolute supply freeze across the wider technology market:
- Chinese Fab Expansion: Domestic suppliers such as CXMT continue ramping up DDR4 and early DDR5 wafer lines, creating alternative supply pipelines for lower-tier markets.
- Enterprise Budget Compression: Escalating memory component prices force data centers to slow down server upgrade cycles, moderating baseline orders.
- Cyclical Capital Discipline: Memory vendors hesitate to overbuild fabrication plants, remembering previous historic oversupply crashes that followed sudden tech booms.
ColdFusion Breaks Down Tech Giants Hoarding Global Memory Supply
ColdFusion pointed out that OpenAI had already locked down around 40% of the worldwide supply of high-bandwidth memory for its ambitious computing plans, alarming peers across Silicon Valley. According to ColdFusion, this massive enterprise hoarding left other hyperscalers scrambling for remaining factory production runs.
ColdFusion illustrated this panic by noting that tech buyers from major American cloud companies booked extended hotel stays in Pangyo and Pyeongtaek, South Korea, attempting to negotiate directly with Samsung and SK Hynix.
ColdFusion described how memory executives face immense pressure, citing SK Group Chairman Chey Tae-won: “These days we’re receiving many requests for memory suppliers from so many companies that we’re worried about how we’ll be able to handle them all. If we fail to supply them, they could face a situation where they can’t do business at all.”
ColdFusion observed that purchasing an individual 256 GB memory bundle can exceed the price of an RTX 5090 graphics card, illustrating severe markups among distributors.
ColdFusion quoted an observation from the CEO of fabless designer Phison, who stated that many consumer electronics manufacturers “will go bankrupt or exit product lines” by the end of 2026 due to the AI memory crisis. As long as tech titans channel capital into model training clusters, global memory output will remain bent toward specialized AI hardware.